UK eCommerce Ads, September 2026: The Movie-Style Ad Is Growing, and the Big Dog Lost Just a Hair
Scope: every category the eCommerceBenchmark Ad Library tracks in the UK, 892 brands and 21,374 UK ads active in September 2026. This cut carries no per-industry and no per-platform split. Where we say "the whole market", we mean all industries and countries together in September 2026: 68,341 ads from 2,573 brands.
Picture a quiet month in the UK ad world. Then look closer: two ad styles moved, and one of them is about to be on every brief.
We checked 21,374 UK ads that were live in September 2026. The month moved by fractions of a point. That is the whole story, and it is a useful one.
Cinematic B-roll went from 4.7% of UK ads in August to 5% in September. That is 1,074 ads from 247 brands. Product Demo Close-Up slipped from 9% to 8.9%. It is still the biggest concept in the set. Nothing else we track lost anything at all [eCommerceBenchmark Ad Library, 2026].
- Nothing in the UK gave you a reason to retire an ad style. The biggest one lost a tenth of a point. That is a rounding error with a minus sign.
- The movie-style ad is a slow, wide rise. 247 UK brands run it. It is a habit, not one brand shouting.
- The UK looks a lot like the whole market. So you can borrow the market's lessons, with a few small UK twists we show below.
A creative concept is defined as how an ad is staged on screen: the shape a shopper takes in before reading a word. Let's start with the one that grew.
Cinematic B-roll: 5% of UK Ads, Up From 4.7%
Cinematic B-roll is the clearest UK gain of the month. It filled 5% of all UK ads active in September 2026, up from 4.7% in August. That is a rise of 0.3 points, on 1,074 ads from 247 brands [eCommerceBenchmark Ad Library, 2026].
Here is a small trap. Each share counts every ad running in the month, not only the ads launched in it. So this is not a launch burst. It is the same big pile, with a slightly wider slice for movie-style ads. Think of a pizza where one slice got a bite bigger.
The brand count is the part worth a second look. 247 UK brands ran at least one ad in this lane. That is a wide habit, not a few brands filling a row with many ads. What the row cannot tell you is who got anything back. A share says what brands ran, not what they earned.
So how does the UK compare with everyone else? Here are the two big concepts side by side, UK against the whole market in September.
Share of ads by concept, UK against the whole market. Source: eCommerceBenchmark Ad Library, 2026.
Nearly the same. Cinematic B-roll sits a touch higher in the UK. The whole market also moved up that month, from 4.6% to 4.9%. So the UK is walking in step with everyone, not running ahead of them.
Now the other side of the story. The biggest lane took a tiny step back.
Product Demo Close-Up Slipped to 8.9% and Is Still the Largest Concept
Product Demo Close-Up is the only UK concept we track that lost any share. It came down to 8.9% of UK ads in September, from 9% in August. That is a fall of 0.1 points. It is also the biggest lane in the set, on 1,906 ads from 362 brands [eCommerceBenchmark Ad Library, 2026].
A fall in share means that lane filled a slightly smaller part of the month. Nothing here records a brand stopping an ad. And concept shares rest on fewer ads than the other things the library tracks, so compare a concept only with another concept.
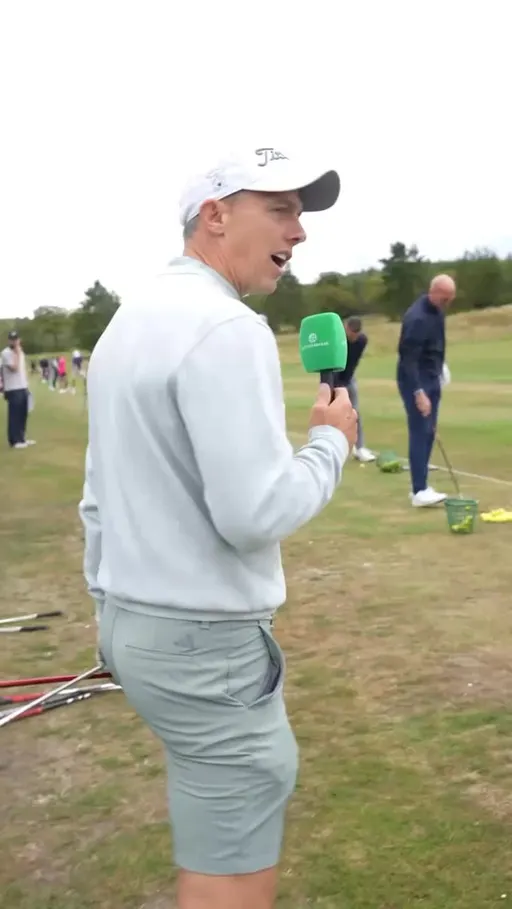
The longest-running UK ad we can show in this lane is from golfclubs4cash.co.uk. It opens with "Ramsdale, uh, can you try and hit this?" and has been on air 375 days. A run that long means somebody kept paying to keep the ad live. It never means the ad sold anything.
Here is a fun contrast. In the whole market, this same concept held at 9.1% in both months and did not move. In the UK it gave up a tenth of a point. Is that a UK trend? We would not bet on it. A tenth of a point is a small step on a very big pile.
Two smaller lanes gained too. They are tiny, but they come with real ads, and one is in German.
Where the Deal Leads the Layout: the Two Smaller Gains
An offer-first banner is defined as a layout where the deal is the biggest thing on screen and everything else is arranged around it. Two smaller UK lanes gained as well.
UK share of ads, September against August. Source: eCommerceBenchmark Ad Library, 2026.
Offer-first banner went from 0.7% of UK ads in August to 0.8% in September, on 162 ads from 70 brands. Montage went from 0.7% to 0.9%, on 184 ads from 51 brands. That is a move of 0.2 points [eCommerceBenchmark Ad Library, 2026].
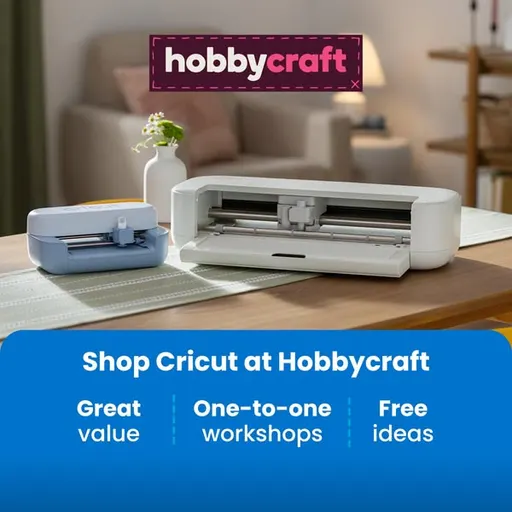
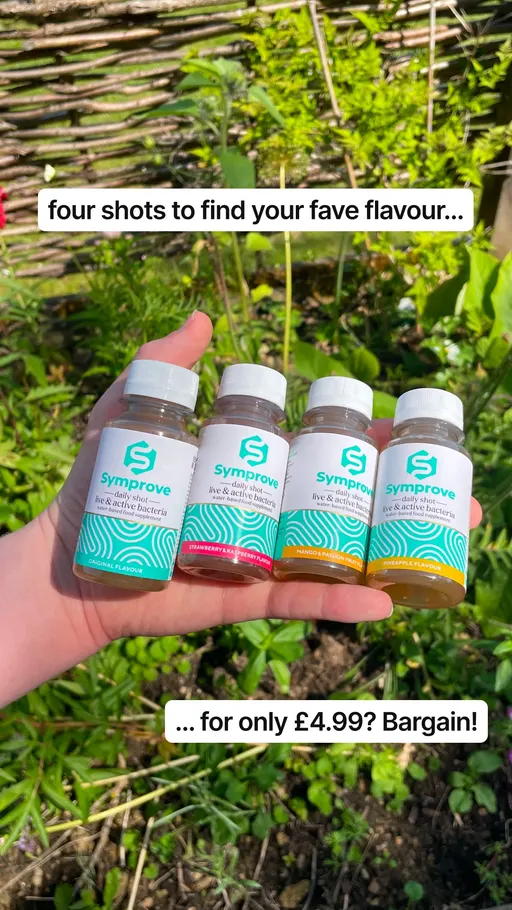
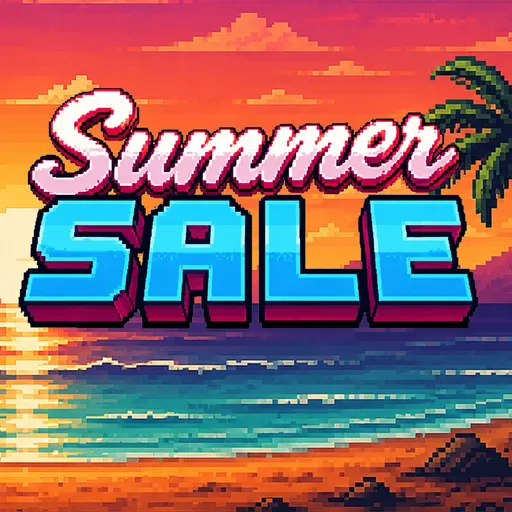
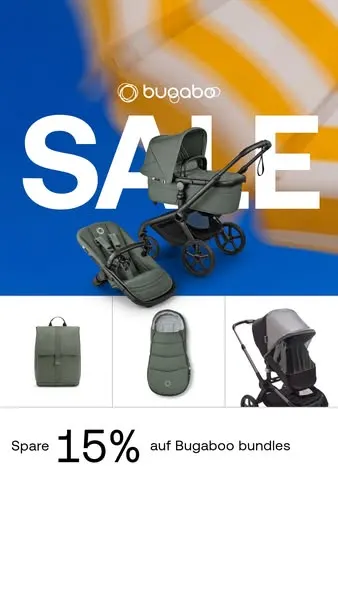
The four UK ads above are all offer-first, and all four ran on Meta. One of them, bugaboo.com, is in German. We quote it as written, with a plain English translation beside it.
Both lanes are small. Offer-first sat on 162 ads and Montage on 184, in a month of 21,374 UK ads. Treat them as a place to add one test, not a place to move a budget.
How do they stand against the whole market? The UK is right with the market on Montage, and a bit behind on the deal-first layout.
Share of ads by concept, UK against the whole market. Source: eCommerceBenchmark Ad Library, 2026.
In the UK, the deal-first layout fills a smaller slice than it does across all markets. Our reading: UK advertisers lean on the product picture more, and less on the price tag. That is our reasoning, not something we measured.
Ready to turn all this into action? The month hands you exactly three small jobs.
What to test
- One staged still against your demo control. Run a single cinematic still beside your longest-running close-up ad. Cinematic B-roll is now 5% of UK ads across 247 brands.
- A deal-first layout in your next banner. Put the offer in the first three words and stop, against your product-led control. Offer-first banner moved from 0.7% to 0.8% of UK ads.
- Hold the demo lane while you test. Keep Product Demo Close-Up where it is and add beside it, not instead of it. It is 8.9% of UK ads from 362 brands.
Where does your account sit?
The eCommerceBenchmark Ad Library sorts your ads into the same hooks, angles, concepts and offers used in this report and shows your mix next to the market, so you can see which shapes you have never shipped.
Audit my creatives, freeSo far we looked at the movers. But most of the story is in what stood still.
The Flat Middle: Nothing Else Fell
Outside those four rows, the UK concepts we track held where they were. Customer Testimonial Reel was 1.1% of UK ads in both months. Side-by-Side Comparison held at 0.6%. UGC Unboxing held at 0.6% too [eCommerceBenchmark Ad Library, 2026].
That is a month of small additions rather than a swap. Three flat rows, three tiny gains, and one tenth of a point lost.
Change in UK share of ads, September against August 2026, in percentage points. Customer Testimonial Reel, Side-by-Side Comparison and UGC Unboxing held flat, so they have no bar. Source: eCommerceBenchmark Ad Library, 2026.
| Concept | UK August | UK September | Change | All markets, September |
|---|---|---|---|---|
| Cinematic B-roll | 4.7% | 5% | ▲ 0.3 pt · +6% | 4.9% |
| Product Demo Close-Up | 9% | 8.9% | ▼ 0.1 pt · -1% | 9.1% |
| Offer-first banner | 0.7% | 0.8% | ▲ 0.1 pt | 1.1% |
| Montage | 0.7% | 0.9% | ▲ 0.2 pt | 0.9% |
| Customer Testimonial Reel | 1.1% | 1.1% | held | 1.0% |
| Side-by-Side Comparison | 0.6% | 0.6% | held | 0.7% |
| UGC Unboxing | 0.6% | 0.6% | held | 0.4% |
One more UK twist from that table. UGC Unboxing is 0.6% of UK ads, against 0.4% for the whole market. It is small, but the UK leans on it a bit more.
That brings us to the one move this month tempts you into, and why it costs more than it looks.
The Mistake: Retiring a Lane Over a Tenth of a Point
The brief this month invites a rotation out of Product Demo Close-Up, because its row carries a minus sign. It is tempting. A riser is easier to sell in a meeting than holding a control.
The cost shows up when a whole market does it at once. The lane 362 brands were filling empties on the smallest move in the data, 0.1 points [eCommerceBenchmark Ad Library, 2026]. Hold the control, add one test beside it, and judge that test on your own numbers rather than on a share that barely moved. Time on air, not sales, is all the market data can give you.
Your test card
Here is the first test from this article, set up the way a media buyer would run it. Fill in the blanks with your own numbers, and write them down before you launch.
| Hypothesis | One staged cinematic still next to my demo control will land within its cost per purchase for UK shoppers. |
| Change only this | The concept only: one staged still of the product in use. |
| Keep the same | Product, offer, UK audience, placement and budget split. Keep the demo control running. |
| Funnel stage | Say first whether this ad is for prospecting (cold) or retargeting (warm). A deal in the first line is often right for warm audiences and wrong for cold ones, so test it where the ad will really run. |
| Setup | One control and one variant, same audience, same placement, even budget split. Do not edit either ad while the test runs. |
| How long and how much | Until each version has about 50 purchases, or two full weeks, whichever comes later. This is general testing practice (Meta's own learning-phase guideline is about 50 results per ad set per week), not a library finding. |
| Success metric | Cost per purchase, not clicks. |
| Stop rule | Pause a variant that has spent about 3 times your target cost per purchase with no purchase. If it is close, keep it running. |
| What counts as a win | The variant beats the control on the metric by an amount you would act on, and still does in a second week. |
Key takeaways
- Cinematic B-roll rose from 4.7% to 5% of UK eCommerce ads, on 1,074 ads from 247 brands [eCommerceBenchmark Ad Library, 2026].
- Product Demo Close-Up slipped from 9% to 8.9%, the only one of the tracked UK concepts to lose any share.
- Product Demo Close-Up is the largest concept in the set at 8.9%, on 1,906 ads from 362 brands.
- Nothing in the UK set fell by more than 0.1 points, so a rotation brief has no faller to point at.
- All of this is read against 21,374 UK ads active in September 2026, every ad running in the month and not only the ones launched in it.
- The UK sits close to the whole market: Cinematic B-roll 5% against 4.9%, Product Demo Close-Up 8.9% against 9.1%, and a smaller Offer-first banner lane, 0.8% against 1.1%.
Questions
September gave UK advertisers no lane to retire. Cinematic B-roll took 5% of UK ads, Product Demo Close-Up came down a tenth of a point and held the biggest lane in the set, and three more rows did not move at all. So do the small job instead of the big one. Pull your own September ads and sort them into four boxes: Cinematic B-roll, Product Demo Close-Up, Offer-first banner, Montage. Count what is in each. The empty box is your test for October, and the full one is your control. Judge both on your own numbers, because the market share barely moved and it cannot tell you what anything earned.